

Whole life insurance is permanent coverage. It pays a fixed death benefit whenever the insured dies, as long as premiums are paid, and it builds cash value along the way. For agents, the sale rarely closes in one call. Clients compare it with term, ask about cash value and wait for an answer. The agents who explain the product clearly and follow up fast tend to be the ones who write the policy. This guide covers the product mechanics agents are asked about most, then how to keep the conversation moving with the tools in CallBack CRM.
TL;DR
- Whole life gives a fixed death benefit for life, level premiums and a cash value that grows on a schedule set in the contract.
- Dividends exist only on participating policies and are never guaranteed. Loans and withdrawals reduce the death benefit and can have tax effects.
- Term costs less per dollar of coverage up front. Whole life costs more but does not expire. The client’s goal decides which fits.
- Most whole life prospects need several touches before they decide. Automated SMS, email and voicemail follow-up keeps those touches on time.
- CallBack CRM starts at 97 USD per month on the Professional plan.
Table of Contents
- What whole life insurance offers
- The four guarantees agents should be able to name
- Premiums and payment options
- Cash value and dividends
- Loans, withdrawals and taxes
- Types of whole life
- Whole life compared with term, endowment and universal life
- Comparing policies on the right measures
- Following up on whole life leads
- Promo: CallBack CRM for insurance agents
- Perspective
- FAQ
- Sources
What whole life insurance offers
The National Association of Insurance Commissioners (NAIC), the association of state insurance regulators, describes whole life as a fixed amount of insurance over the insured’s lifetime, with the benefit payable only at death. The policy builds tax-deferred cash value and allows borrowing against it. State law also requires nonforfeiture values, which means the client keeps some value if the policy lapses or is surrendered.
State Farm explains that a whole life policy is designed to stay in force for life as long as the owner meets the policy obligations, regardless of later changes in health. Level premiums set aside a portion that earns interest. That reserve is what lets the insurer pay the full death benefit while premiums stay level.
Three features carry most client conversations:
- Lifetime protection. The coverage does not expire on a term date.
- Level premiums. The amount is fixed at issue in a traditional policy.
- Cash value. A savings component the client can borrow against or draw on.
The four guarantees agents should be able to name
Guardian explains that actuaries set four guaranteed values when the policy is underwritten:
- A level premium that is guaranteed never to change.
- A death benefit that is guaranteed never to decrease.
- A cash value guaranteed to grow at a set rate until it equals the face amount at a specified age, typically 100 or 121.
- A guaranteed endowment that pays the death benefit if the insured is alive at that age.
The terminal age matters when a client asks how long the policy lasts. NerdWallet notes that whole life generally lasts the insured’s entire life, though many policies end at age 100. Agents should check the contract’s terminal age for the specific product and state it plainly.
Premiums and payment options
The New York Department of Financial Services states that in a traditional whole life policy the scheduled premiums generally stay level and fixed for the insured’s life. Some modified-premium policies start lower and later rise to a higher level amount. The department points consumers to the policy’s data or specifications page, usually page 3, for the amounts and the payment period.
That page is worth opening with the client during the call. It shows what is paid, for how long and whether the premium steps up.

Payment length varies by product. USAA lists payment options of 20 years, until age 65, or for the life of the policy. A shorter payment period means higher premiums. The NAIC classes limited payment policies as a type of whole life: premiums are paid over a shorter span, cash value builds faster than in ordinary life, and the protection still lasts for life. Single premium whole life buys lifetime protection with one lump sum and creates cash value immediately.
Matching payment length to the client
| Client situation | Structure to discuss |
|---|---|
| Wants the lowest permanent premium | Ordinary level premium, paid for life |
| Expects to retire and wants no premiums later | Limited pay, such as 20 years or to age 65 |
| Has a lump sum and wants lifetime coverage | Single premium |
| Wants lower early premiums | Modified premium, with the later step-up shown on the policy pages |
The table is a starting point for the conversation. Product availability depends on the carrier and state.
Cash value and dividends
Cash value comes from premiums that exceed the cost of insurance in the early years. The American Council of Life Insurers (ACLI) explains that in traditional whole life, early premiums are higher than the actual cost of insurance. The excess is held in reserve and grows from investment earnings and future premiums, which fund the rising cost of coverage later in life.
Two points to set expectations with clients:
- Growth is gradual. NerdWallet reports that guaranteed cash value grows at a fixed insurer-set rate, typically 1% to 3.5%, and that it can take years or even a decade to build enough to use.
- Early years build faster. Investopedia notes that cash value grows quickly when the insured is young and more slowly later, because more of each premium covers the rising cost of insurance.
How dividends work
Dividends apply only to participating policies, which are typically issued by a mutual life company owned by its policyholders. MetLife’s whole life FAQs describe a dividend as a return of premium when the policy performs better than expected, based on investment returns, mortality, persistency and expenses. Dividends are not guaranteed.
State Farm lists the ways a dividend can be used:
- Take it as cash.
- Reduce premiums.
- Buy paid-up additions.
- Leave it with the insurer to earn interest.
- Purchase one-year term insurance.
- Pay up the policy earlier.
Paid-up additions are the option clients ask about most. MoneyGeek explains that each addition adds death benefit and cash value and earns its own future dividends, which creates a compounding effect. Guardian states that it has paid dividends every year since 1868, while noting that none are guaranteed. The honest framing for a client is that dividend history is context, not a promise.
Loans, withdrawals and taxes
Cash value is the feature that separates whole life from term in most client questions. It is also where mistakes are costly, so the mechanics need to be exact.
MassMutual’s tax guide explains that policyowners can borrow against cash value or partially surrender paid-up additions at any time. Loans and partial surrenders reduce the surrender value and the death benefit. For a policy that is not a modified endowment contract, distributions are tax-free up to cost basis, and loans are not treated as distributions. A loan outstanding at death is repaid from the proceeds without creating taxable income.
MetLife adds that loans accrue interest. Investopedia observes that unpaid loans and withdrawals can chip away at the death benefit or wipe it out.
Lapse with a loan
This is the case to explain before a client borrows. State Farm states that if a policy lapses or is surrendered with a loan outstanding, the loan is treated as taxable income for that year to the extent of gain in the policy. Rates Chaser gives an example: a $200,000 loan against an $80,000 basis could create $120,000 of taxable income. Keeping the policy in force and the loan interest managed is what avoids the problem.

Modified endowment contracts
MassMutual explains that a modified endowment contract (MEC) results when a federal premium limit is exceeded. A MEC loses the favorable treatment: dividends, partial surrenders and loans are taxed earnings first, and distributions before age 59½ carry a 10% tax penalty. Agents who design large or single-premium policies should confirm MEC status with the carrier illustration.
Agents explain how the product works. Specific tax questions go to the client’s tax professional.
Types of whole life
The NAIC lists these variations:
- Nonparticipating, with no dividends.
- Participating, which can pay dividends.
- Indeterminate premium.
- Ordinary level premium.
- Limited payment.
- Single premium.
The NAIC frames the differences as mainly about dividend participation and premium structure. Participating policies trade a higher cost for the flexibility dividends provide.
Final expense policies are a common whole life use. They are built around end-of-life costs, and they are often smaller face amounts. Guaranteed acceptance versions exist for clients with health problems. The Department of Veterans Affairs, for example, offers VALife as guaranteed acceptance whole life for eligible veterans, with up to $40,000 of coverage in $10,000 increments and cash value.
Whole life compared with term, endowment and universal life
The Connecticut buyer’s guide, part of state regulations, describes three basic kinds of life insurance. Term pays only if death occurs within a set period and gives the largest immediate protection per premium dollar. Whole life protects for as long as the insured lives, at premiums several times higher than initial term but lower than renewing term into later years. Endowment pays the policyholder if they live to a certain age, with higher premiums and cash values than whole life.
| Feature | Term | Whole life | Universal life |
|---|---|---|---|
| Coverage length | Set period | Lifetime | Lifetime, if funded |
| Premiums | Level during term | Level, scheduled | Flexible |
| Cash value | None | Guaranteed growth | Varies by design |
| Best for | Temporary needs, tight budgets | Permanent needs, estate and final expense | Clients who want flexibility |
The NAIC buyer’s guide separates whole life from universal life by premium structure: whole life follows a set schedule, while universal life allows flexible premiums as long as enough is paid to keep the policy in force. NerdWallet adds that guaranteed universal life sits between term and whole life on cost, with lifetime coverage and fixed cash value growth.
Term costs less up front, so a fair comparison states what the client is buying. Whole life fits clients who want a benefit that does not expire and a policy value they can use during life. Term fits clients who need the most coverage for a limited period.
Comparing policies on the right measures
The Connecticut guide advises comparing policies using the Surrender Cost Index and the Net Payment Cost Index. It warns that small index differences can be offset by policy features or service quality, and that one company’s good buy does not make all its policies equally good.
A clear presentation usually covers:
- The premium, the payment period and whether it steps up.
- The guaranteed cash value schedule, separate from any illustrated dividends.
- Whether the policy is participating.
- The terminal age.
- How loans and withdrawals change the death benefit.
- The nonforfeiture options if the client stops paying.
Putting guaranteed and non-guaranteed figures in separate columns keeps the discussion accurate.
Following up on whole life leads
Whole life prospects ask questions, compare quotes and go quiet. The sale tends to depend on who responds first and who keeps showing up with useful answers. Manual follow-up breaks down as the lead count grows.
CallBack CRM is built for insurance sales workflows. It automates follow-up by SMS, email and voicemail and keeps pipeline stages in one place. Agents can set a sequence that sends the first message right after a lead comes in, then schedules the next touches. The agency’s own guides cover how to set this up:
- Insurance lead nurturing covers the basics of staying in contact until a lead is ready.
- Sales automation workflows show how to build the sequence.
- The final expense funnel walks through a six-stage automated contact plan that applies to whole life based final expense leads.
- Email automation for insurance covers compliance and CRM setup.
A workable whole life sequence follows the questions clients ask in order. The first message confirms the request. The second explains how the policy works in plain terms. The third addresses cost against term. The fourth offers a call to review the policy pages together. Each message can be written once and sent automatically.
CallBack’s messaging uses unique message hashing, iMessage deliverability and carrier-approved verbiage, which are practices aimed at getting texts delivered.
Promo: CallBack CRM for insurance agents
CallBack CRM is an AI-powered CRM and sales automation platform for insurance agents, agencies and IMOs. It includes pipeline management, automated follow-up by SMS, email and voicemail, funnel and website builders, reporting, and mobile and desktop apps. Its specialties include whole life, final expense, mortgage protection, indexed universal life, annuities, term and Medicare.
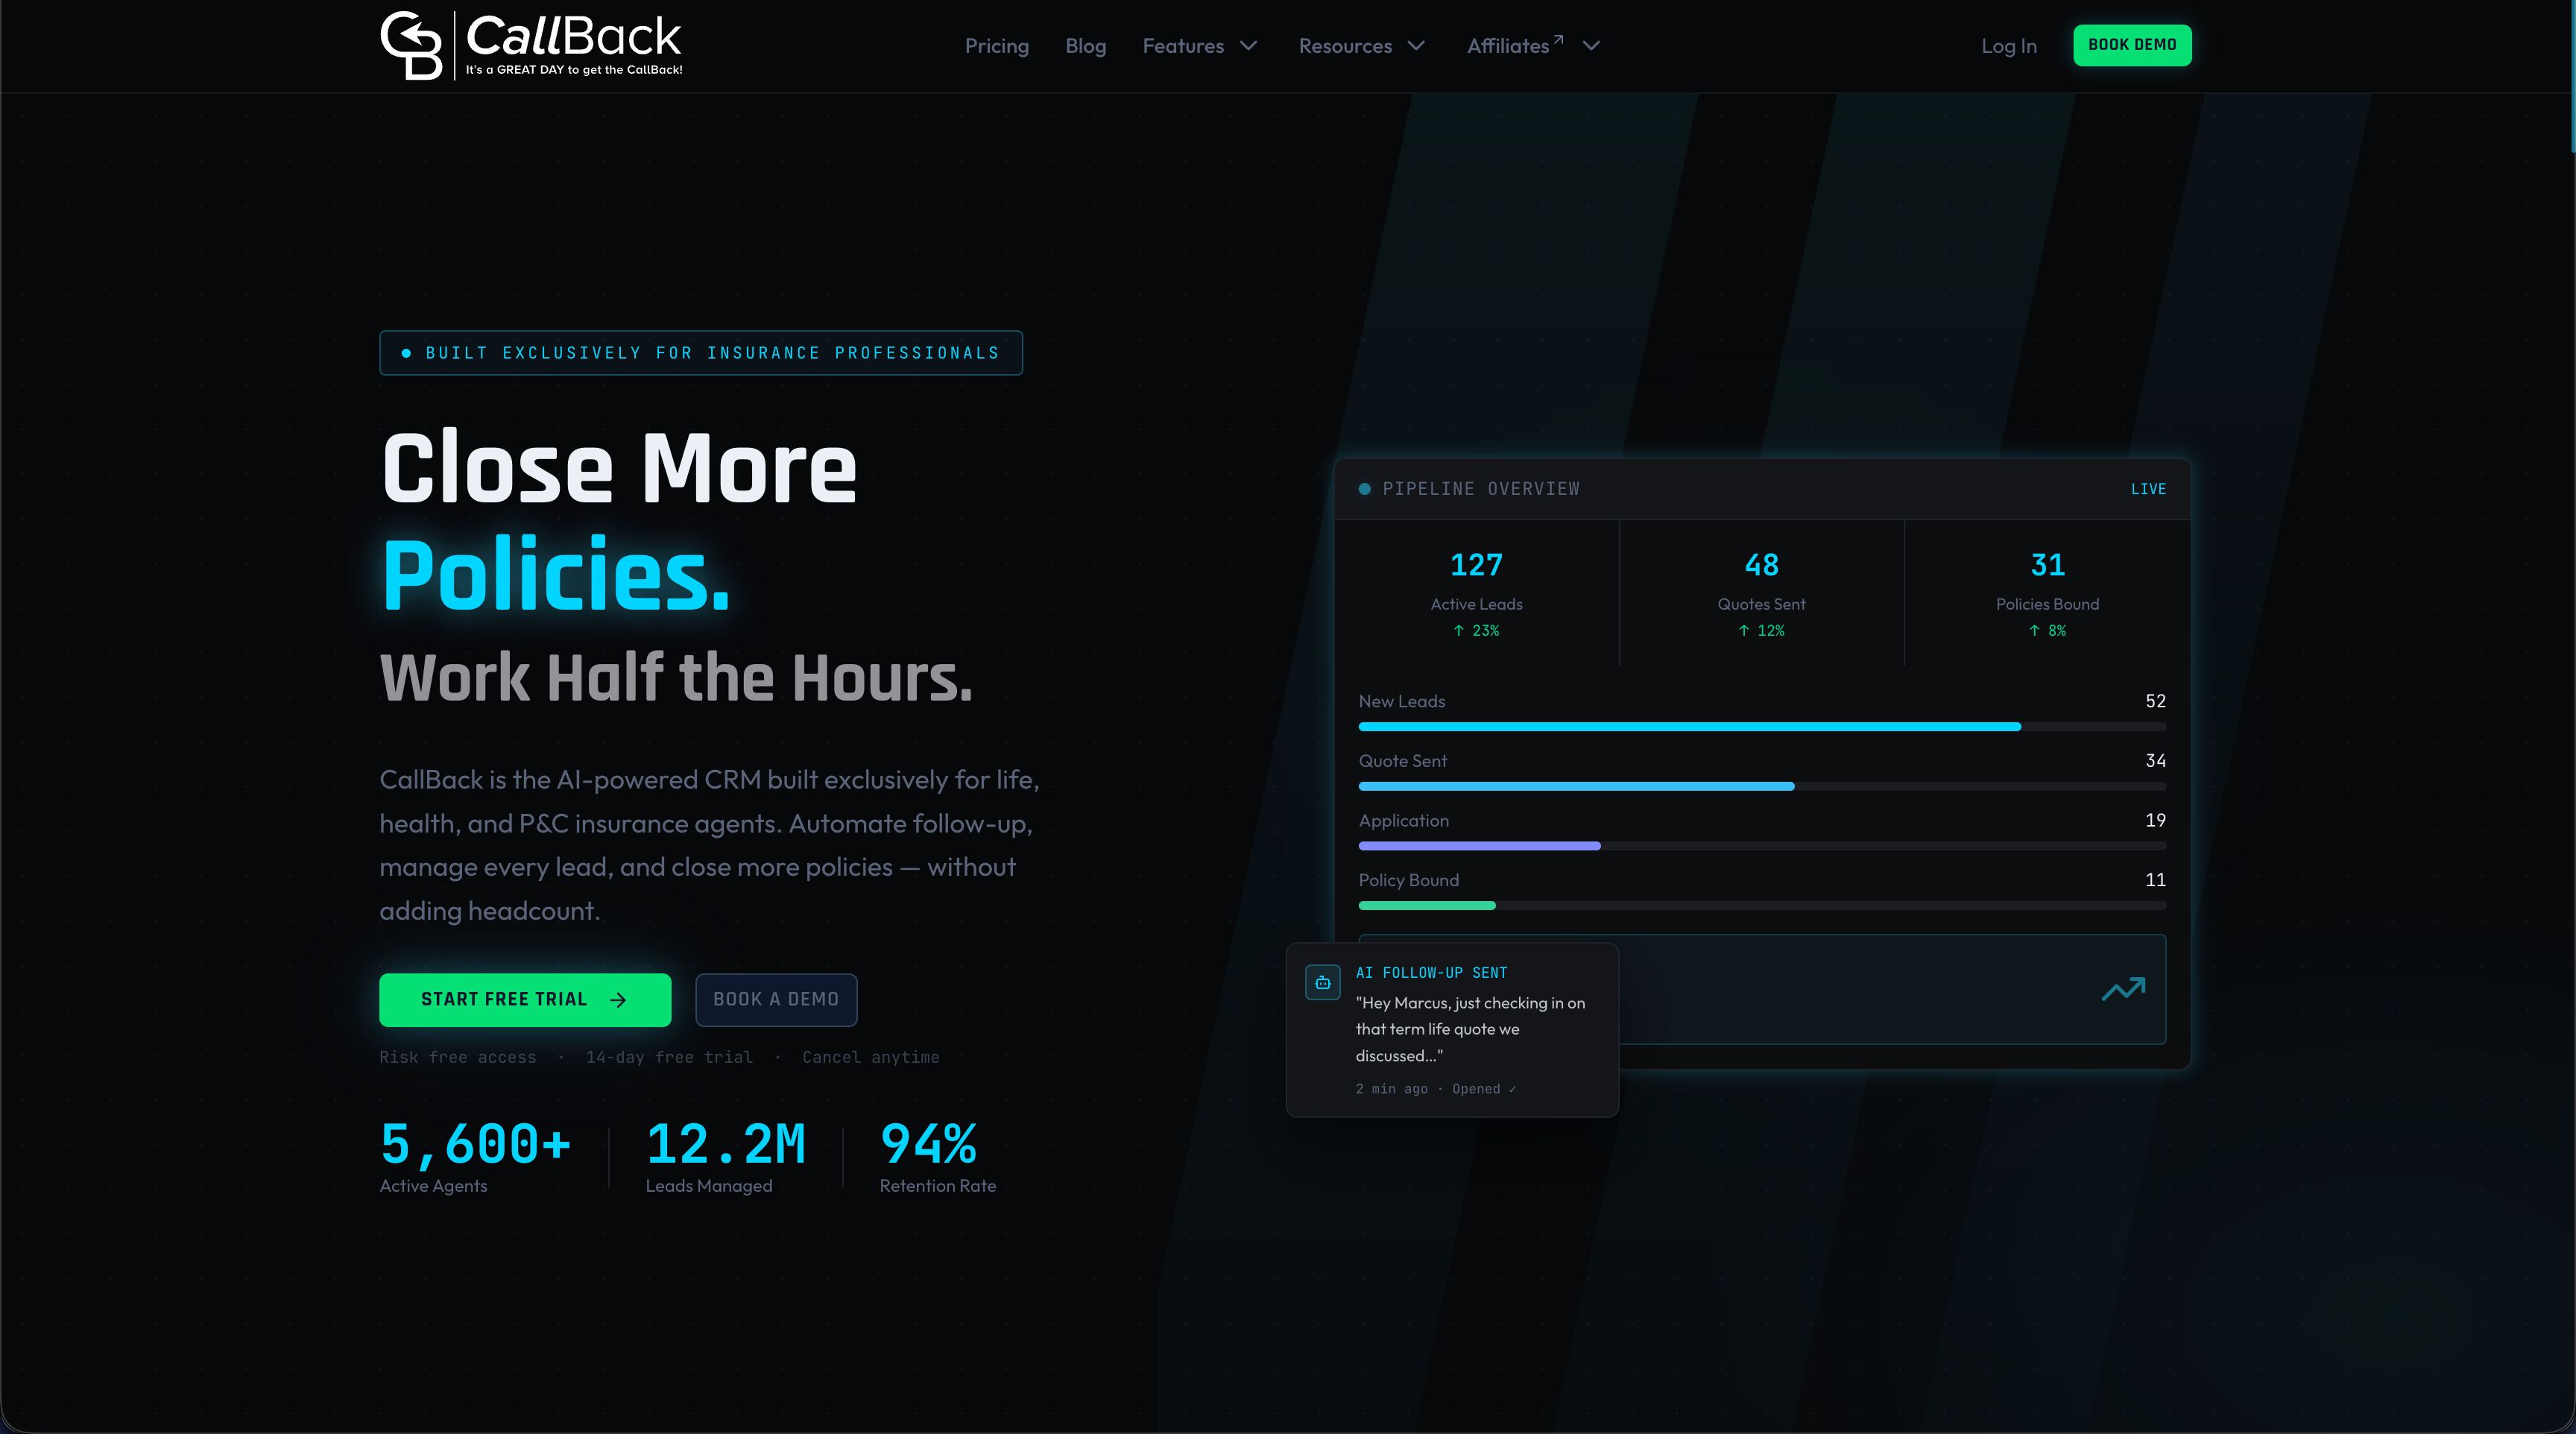
The Professional plan is 97 USD per month. Agencies can use the Enterprise plans: 297 USD per month for 10 full CRM accounts, 397 USD per month for 25 and 497 USD per month for 60. The Unlimited AI Employee Bundle is 127 USD per month. Phone numbers are 2.30 USD per month per number. SMS, email and AI usage are billed at wholesale rates, and the full list is on the fees page. Plans and the platform overview are also at callbackcrm.com.
Perspective
We built CallBack for agents who sell products like whole life, where the client needs time and clear answers before deciding. A prospect who asks about cash value on Monday is often comparing three offers by Wednesday.
What we see as the main problem in this sale is speed and consistency. The product is easy to explain well once. It is hard to explain well to forty leads a week while also writing business. That is the work we automate: first contact, follow-up, reminders and pipeline tracking.
Our approach is to build the sequence around the questions clients ask: how long the coverage lasts, what the premium is, what cash value means and how it compares with term. When that sequence runs on its own, the agent spends calls on the conversations that are ready to move.
We designed the platform for insurance workflows, with industry-tailored pipelines and AI-powered follow-up, so agents do less setup than they would with a generic CRM.
Kyle
FAQ
What does a whole life insurance policy offer?
It offers lifetime coverage with a fixed death benefit, level premiums and cash value that grows at a rate set in the contract. The cash value can be borrowed against. State law requires nonforfeiture values if the policy lapses or is surrendered, according to the NAIC.
Are whole life dividends guaranteed?
No. Dividends are available only on participating policies, and they depend on the insurer’s results. MetLife describes them as a return of premium when the policy performs better than expected. Agents should show guaranteed values and illustrated dividends separately.
What is the difference between whole life and endowment insurance?
Whole life pays a death benefit whenever the insured dies. Endowment pays the policyholder if they live to a certain age, and pays the beneficiary otherwise. The Connecticut buyer’s guide states that endowment has higher premiums and cash values than whole life and the least death protection per premium dollar.
What is a limited pay life policy?
It is a type of whole life in which premiums are paid over a set number of years, such as 20 or until age 65, and coverage lasts for life. Premiums are higher than on an ordinary policy, and cash value builds faster, according to the NAIC.
Sources
- NAIC: Whole life insurance
- NAIC: Life Insurance Buyer’s Guide
- State Farm: Whole life insurance
- Guardian: How whole life insurance works
- New York DFS: Will scheduled whole life premiums change over time
- USAA: Whole life insurance
- NerdWallet: How whole life insurance works
- ACLI 2024 Fact Book, Chapter 7
- MoneyGeek: Life insurance dividends
- MassMutual: Income taxation of whole life insurance
- MetLife: Whole life FAQs
- Investopedia: Understanding whole life insurance
- Rates Chaser: Life insurance cash value
- Connecticut insurance buyer’s guide
- VA: VALife