

Insurance chatbots are used for six main jobs: answering policy questions, qualifying leads, supporting quotes, onboarding new clients, taking claims intake, and routing hard cases to a licensed person. The NAIC describes chatbots as tools that answer common customer questions, provide basic information, and assist with simple transactions at any time of day. This guide covers each use case, real examples with reported results, and where a chatbot should stop and hand off to a human.
TL;DR
- Chatbots work best on repeatable tasks: FAQs, lead capture, appointment booking, policy servicing, and first notice of loss.
- Reported results exist. Allstate’s consumer bot fully managed about 400,000 of one million conversations. Lemonade reports policies bound in as little as 90 seconds.
- Coverage advice, policy interpretation, and coverage changes stay with a licensed agent.
- Agents and agencies get the most value when the chatbot feeds a CRM with follow-up workflows, not when it runs as a stand-alone widget.
- Insurers stay responsible for fairness, accuracy, and privacy when they use AI.
Table of Contents
- Why insurance uses chatbots
- Use case 1: Answering policy and coverage FAQs
- Use case 2: Lead capture and qualification
- Use case 3: Quote support and product guidance
- Use case 4: Appointment booking and sales follow-up
- Use case 5: Client onboarding
- Use case 6: Claims intake and status updates
- Use case 7: Payments, renewals, and policy servicing
- Use case 8: Cross-selling and policy reviews
- Use case 9: Internal knowledge support for agents
- Use case 10: Handoff to a human
- Real results reported so far
- Rules and risks to plan for
- Perspective
- Setting up a chatbot in an insurance CRM
- How to choose where to start
- FAQ
- Sources
Why insurance uses chatbots
Insurance has a high volume of repetitive questions. Clients ask for ID cards, billing dates, coverage summaries, and claim status. Prospects ask for quotes outside office hours. A chatbot answers these at any hour and records the details.
Adoption is broad. In NAIC survey data, 88% of auto insurers, 70% of home insurers, 58% of life companies, and 92% of health insurers reported they use, plan to use, or are exploring AI/ML models. Those figures cover AI in general, not only chatbots, but chatbots are one of the most visible forms.

The focus is also shifting. EY observes that insurers are moving investment from back-office AI to front-office, customer-facing uses. About 68% of insurers are investing in chatbots to drive cross-selling and value-added products, and life and annuity firms lead at 76%, according to the same EY survey.
For an independent agent or an agency, the practical question is narrower: which tasks can a chatbot take over without adding risk, and which should stay with a person.
Use case 1: Answering policy and coverage FAQs
This is the most common starting point. The bot answers questions that have a fixed answer:
- Where to find an ID card or certificate of insurance
- When a premium is due and how to pay it
- Which documents are needed for a change of address
- Office hours and how to reach the agent
- General definitions, such as what a deductible or a rider is
In life and annuity, the questions get more specific. Deloitte notes that GenAI-enabled chatbots can answer FAQs about annuity snapshots, such as daily change, account performance, surrender value, and contract benefits.
The key rule is the line between information and advice. A bot can state what a client’s policy document says. It should not tell a client whether a coverage fits a situation. That decision belongs to a licensed agent.
Use case 2: Lead capture and qualification
A website visitor who asks about final expense, Medicare, or mortgage protection is a prospect. A chatbot can start the conversation immediately and ask the same questions an agent would ask first:
- What type of coverage is the visitor interested in?
- What state does the visitor live in?
- What is the age range and the timeline?
- What is the best way to reach the visitor: call, text, or email?
The answers are saved to a contact record and scored. High-intent leads go to the agent right away. Others enter a nurture sequence. The result is that agents spend time on people who answered, not on cold lists.
This ties directly to lead generation workflows. CallBack covers the process in more detail in its guide on how to automate lead generation for insurance agents.
Use case 3: Quote support and product guidance
A quote is, in the words of the California Department of Insurance, an estimate of the cost of insurance based on information supplied by the applicant. A chatbot is well suited to collecting that information. It asks for the details in a fixed order, checks for missing fields, and passes a complete request to the agent or to a rating tool.
Some carriers go further. Lemonade has reported that its bots, Jim and Maya, can secure a consumer policy in as little as 90 seconds. That is a direct-to-consumer model. Most independent agents use the bot for the intake half only: collect, confirm, book a call.
Chatbots also help agents internally. Allstate built an assistant called ABIe for its own agents. It answers questions, finds critical documents, and gives step-by-step help for quoting and issuing Allstate Business Insurance products. Allstate’s ABIe handles over 25,000 agent inquiries each month, according to the same case study, which reduced reliance on call centers for FAQs.

Use case 4: Appointment booking and sales follow-up
Most lost sales in insurance come from slow or missing follow-up. A chatbot connected to a calendar can offer time slots in the chat. A workflow can then send a confirmation text, a reminder the day before, and a short message after a missed call.
A typical follow-up sequence for a quote request:
| Step | Channel | Trigger |
|---|---|---|
| Instant reply | Chat or SMS | Form or chat started |
| Booking offer | SMS and email | No appointment after 1 hour |
| Reminder | SMS | 24 hours before the call |
| Missed-call message | SMS or voicemail | Call not answered |
| Quote follow-up | 2 days after the quote |
The timing in the table is an example, not a rule. Each agency should adjust it to its own lead sources and carrier requirements.
For teams building a wider plan, a marketing automation checklist helps map which touches should be automated and which should stay manual.
Use case 5: Client onboarding
After a sale, the first weeks decide whether a client stays. A chatbot can walk a new client through the next steps:
- Confirm that the application was received
- List the documents still needed
- Explain how to set up payment and how to reach the agency
- Send a welcome message with the agent’s contact details
- Ask for a review after the policy is in force
The last step matters for reputation. Automated review requests sent at the right moment produce more reviews than ad hoc asks. Document collection can be paired with e-signatures. CallBack’s contracts feature covers signing inside the same system.
Use case 6: Claims intake and status updates
First notice of loss (FNOL) is where chatbots save the most time. Instead of a long form, the claimant describes what happened. Deloitte says generative AI can streamline FNOL by processing incident details in the claimant’s own words and reducing manual form filling. It can also support claim evaluation and settlement.
For agencies, the realistic version is simpler:
- Collect the date, location, and a description of the loss
- Request photos and the police report number
- Give the carrier’s claim phone number and the agent’s direct line
- Send status updates when the carrier posts them
Speed is the benefit. Lemonade has reported settling claims in as little as 3 minutes for simple cases. Complex or disputed claims need an adjuster and a human conversation.
Use case 7: Payments, renewals, and policy servicing
The smaller tasks add up. RightSure’s insurBot saw a spike in March 2020 and handled up to 100 requests per day for quotes, payments, and other services. That shows how a bot absorbs demand when phone lines are busy.
Common servicing tasks include:
- Payment reminders and links
- Renewal notices with a prompt to book a review
- Beneficiary or address change requests, routed to the agent for processing
- Certificate and ID card requests
Renewal outreach is also a retention tool. CallBack’s article on the role of AI in client retention goes into the details.
Use case 8: Cross-selling and policy reviews
EY found that cross-sell is a main reason insurers invest in chatbots. For an agency, the same idea applies to its own book. A bot or workflow can message clients at natural moments: a home purchase, a new child, a birthday that changes Medicare eligibility, or a policy anniversary.
The message offers a review. It does not recommend a product. The agent makes the recommendation on the call. Deloitte also notes that generative AI can personalize marketing content and summarize pre-call journeys to assist agents, so the agent starts the call with context.
Use case 9: Internal knowledge support for agents
Not every chatbot faces the client. Allstate’s ABIe is an internal tool. Earley Information Science describes this type as a knowledge management tool that helps agents find information quickly while in front of customers.
For a small agency, the equivalent is a bot trained on carrier guides, underwriting notes, and the agency’s own procedures. A new agent can ask where a form is or which carrier accepts a certain health history. The answer should always point to the source document so the agent can verify it.
Use case 10: Handoff to a human
The handoff is a use case in itself. A good bot knows when to stop. Utica National’s risk-management guidance is that chatbots are best limited to administrative support, general information, and basic intake. Coverage advice, policy interpretation, and coverage changes remain under licensed-agent control, because the agency stays responsible for inaccurate or misleading outputs.
The California Department of Insurance advises consumers to verify a broker-agent’s license. A chatbot does not hold a license. That is a strong reason to keep recommendations with the person who does.
Tasks to escalate
| Task | Bot can do | Licensed person must do |
|---|---|---|
| Coverage questions | Quote the policy text | Explain what fits the client |
| Quote request | Collect details | Review and present options |
| Claim filing | Collect loss details | Handle disputes, coverage decisions |
| Policy change | Log the request | Process and confirm the change |
| Complaint or distress | Alert the team | Respond personally |
| Health claim denial | Share appeal steps | Review and decide |
On health decisions, the NAIC Consumer Representatives’ 2024 report says human reviewers must have authority to overturn AI determinations and that consumers need a clear appeal path.
Real results reported so far
The published numbers vary by company and by definition, so they should be read as examples, not as benchmarks.
| Example | Reported result |
|---|---|
| Allstate consumer chat channel | 38 to 40% containment, about 400,000 of one million conversations fully managed by the bot |
| Allstate ABIe (agent assistant) | Over 25,000 agent inquiries per month |
| Lemonade Jim and Maya | Policy in as little as 90 seconds, claims in 3 minutes |
| RightSure insurBot | Up to 100 requests per day in March 2020 |
Containment of 38 to 40% is worth noting. It means that even at a large carrier, most conversations still reach a person. A chatbot reduces load. It does not remove the need for staff.
Rules and risks to plan for
The NAIC states that insurers remain responsible for insurance laws, consumer protection, fairness, accuracy, and avoiding unfair discrimination when they use AI. State regulators may ask for explanations of AI used in underwriting, pricing, marketing, or claims, and human oversight stays important.
The NAIC AI principles add accountability, compliance with each jurisdiction’s insurance laws, data retention, and transparency about data and purpose, plus a way for consumers to seek information or recourse.
EY recommends that insurers monitor and audit AI data, set clear privacy and security policies, and build AI governance and risk frameworks.
A practical checklist for an agency:
- Tell users they are talking to an automated assistant.
- Limit the bot to general information and intake.
- Keep a log of conversations and review samples.
- Give a clear way to reach a person.
- Check state rules and carrier requirements for marketing messages and recorded data.
- Use carrier-approved wording for texts and emails.
Perspective
We built CallBack for insurance sales, so our view is shaped by one question: what happens after the chat ends.
A chatbot that answers a question and stops is only half a tool. The value comes when the answer, the contact details, and the next step land in a pipeline, and a follow-up starts on its own. That is why we put chat, SMS, email, voicemail, calendars, and AI assistants in one platform instead of separate tools.
We also think the right limit is clear. AI handles intake, reminders, and routine questions. The licensed agent handles advice. Our workflows are designed to hand the conversation to the agent with the context already saved, so the client does not repeat themselves.
For deliverability, we use unique message hashing, iMessage deliverability, and carrier-approved verbiage, because a good automation is useless if the message does not arrive.
Start with two or three use cases, such as lead qualification and appointment booking. Measure them for a month. Then add more.
Kyle
Setting up a chatbot in an insurance CRM
CallBack is a CRM and sales automation platform built for insurance agents, agencies, and IMOs. It includes pipelines, automated follow-up by SMS, email, and voicemail, AI assistants, funnel and website builders, and reporting.
Published pricing, as listed on the site:
- Professional: $97 per month
- Enterprise: $297 per month for 10 full CRM accounts, $397 per month for 25, and $497 per month for 60
- Unlimited AI Employee Bundle: $127 per month
- Phone numbers: $2.30 per month per number
SMS, email, and AI usage are billed separately. The fees page lists each item. To see the platform first, start from the CallBack homepage.
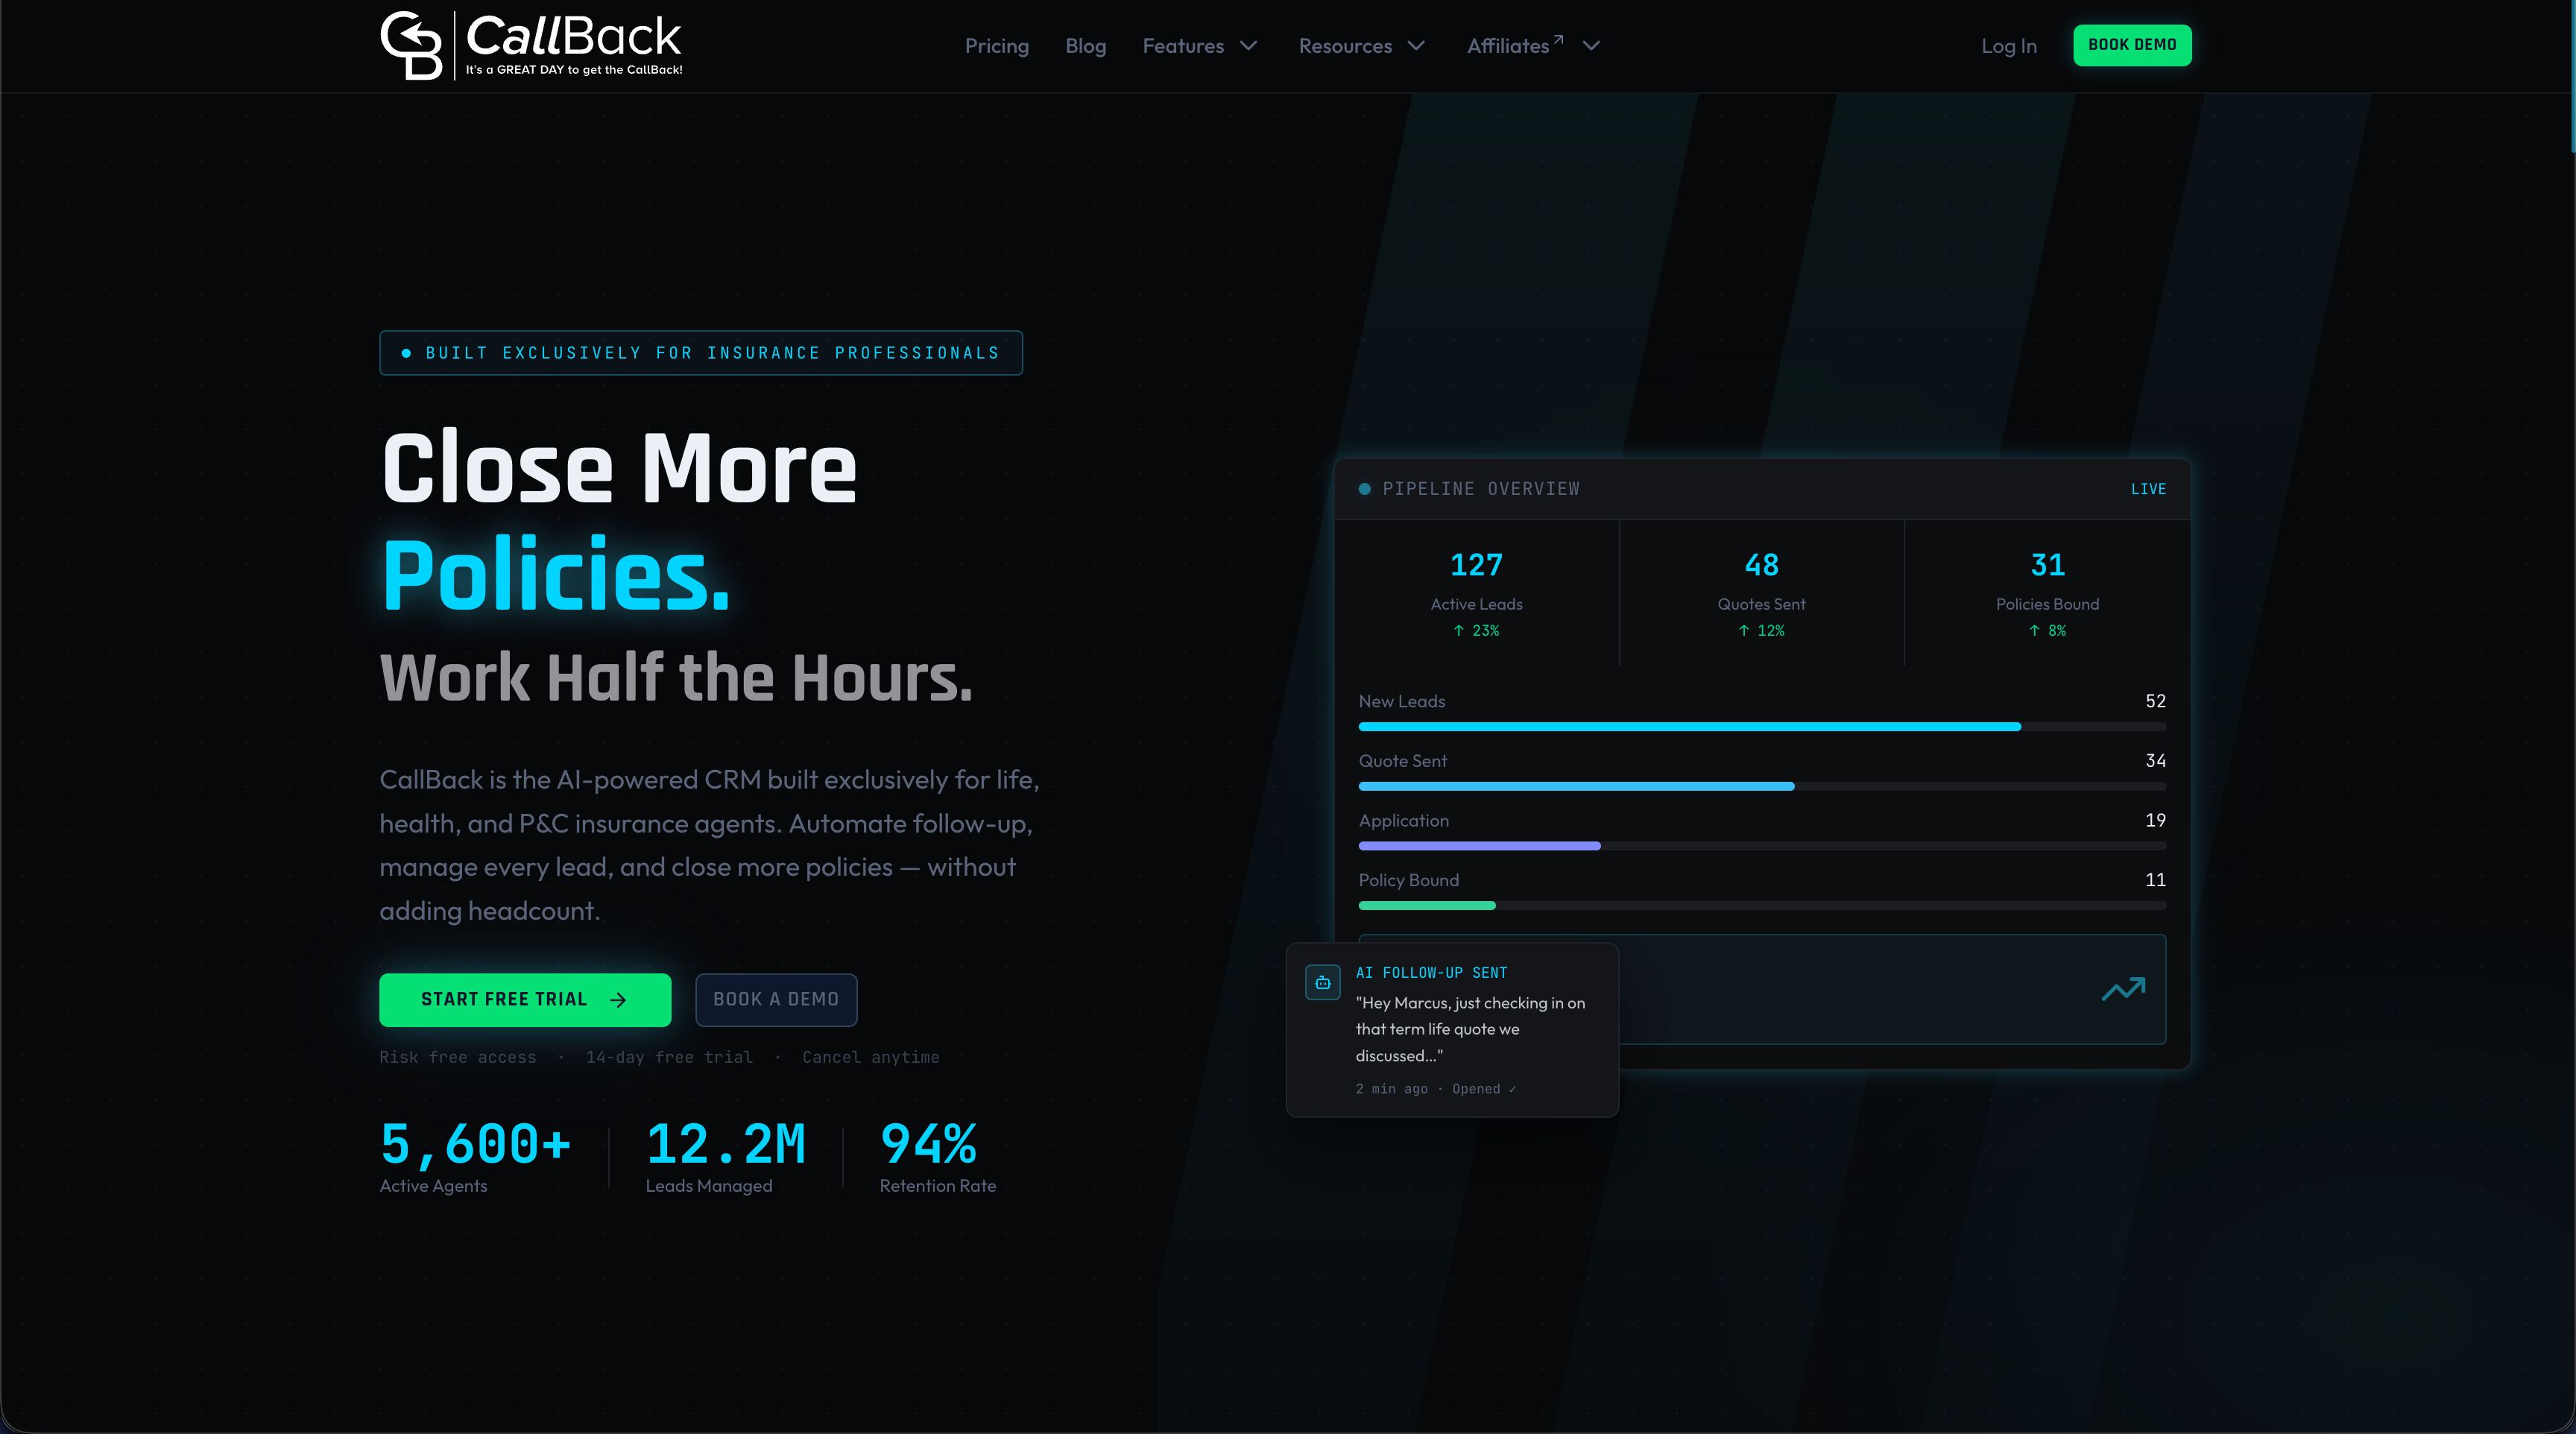
For more on the strategy behind these tools, see the guides on AI customer engagement strategies for insurance agents and AI chatbots in insurance explained.
How to choose where to start
Pick the use case with the clearest payoff and the lowest risk.
- Missed leads after hours. Start with lead capture and appointment booking.
- Heavy phone volume on simple questions. Start with FAQs and servicing requests.
- Slow quote turnaround. Start with quote intake.
- Low reviews or weak retention. Start with onboarding and renewal outreach.
Write down the questions your office answers most often. Those become the first bot answers. Review the logs weekly at first, fix wrong or vague answers, and add escalation rules wherever clients ask for advice.
FAQ
What is the most common use of a chatbot in insurance?
Answering routine questions is the most common. These include billing dates, ID cards, document requests, and basic policy information. The NAIC lists answering common questions and assisting with simple transactions as core chatbot functions.
Can a chatbot sell insurance?
A chatbot can collect details and start a quote, and some direct carriers bind simple policies through chat. For independent agents, the usual model is intake by bot and recommendation by a licensed agent. Coverage advice should stay with the licensed person.
Are insurance chatbots regulated?
There is no single chatbot law, but insurers remain responsible under insurance and consumer-protection rules when they use AI. State regulators may ask for explanations of AI used in marketing, underwriting, pricing, or claims. Agencies should also check carrier and state requirements for messaging.
Which tasks should a chatbot hand off to a person?
Coverage advice, policy interpretation, coverage changes, disputed claims, complaints, and health-related denials should go to a licensed professional or service representative. The bot should pass the full conversation along so the client does not start over.
How should an agency measure a chatbot?
Track how many conversations end without staff help, how many leads book appointments, response time, and client complaints. Allstate’s reported containment of 38 to 40% shows that even strong bots send many conversations to people, so set targets by use case.
Sources
- NAIC: Artificial Intelligence
- NAIC: Chatbots
- NAIC: Principles on AI
- NAIC Consumer Representatives: AI and Health Insurance report
- Deloitte: Transforming customer experience in insurance
- EY: GenAI in Insurance Key Survey Findings
- Earley Information Science: Allstate’s Intelligent Agent case study
- Tietoevry: Allstate’s conversational AI journey
- Insurance Innovation Reporter: RightSure insurBot
- Utica National: AI chatbots in insurance agencies
- California Department of Insurance: Glossary of Insurance Terms
- California Department of Insurance: Commercial Insurance Guide
- Marketing automation checklist for SMBs