

An annuity is a contract between a person and an insurance company. The person pays a lump sum or a series of payments. The insurer agrees to pay income, starting now or later. For agents, the work is explaining these contracts clearly and staying in touch with prospects through a decision that often takes weeks. This guide covers how annuities work, the main types, costs, taxes, and how an agent can organize follow-up with CallBack.
TL;DR
- An annuity turns a lump sum or a series of premiums into income, immediately or at a future date.
- The main deferred types, from lowest to highest risk, are fixed, fixed indexed, registered index-linked (RILA) and variable.
- Costs include surrender charges, rider fees and, on variable contracts, fund and insurance charges. Withdrawals are generally taxed as ordinary income.
- Prospects ask the same questions repeatedly, so a consistent follow-up routine matters as much as product knowledge.
- CallBack is built for insurance agents and lists annuities among its specialties.
Table of Contents
- What an annuity is and how it works
- Types of annuities
- What annuities cost
- How annuities are taxed
- Benefits and tradeoffs for retirement income
- Explaining annuities to prospects
- Following up with annuity prospects
- CallBack for annuity agents
- Our view
- FAQ
- Sources
What an annuity is and how it works
Investor.gov describes an annuity as a contract between you and an insurance company, designed to meet retirement and other long-term goals. The buyer pays a single lump sum or a series of payments. In return, the insurer makes periodic income payments, beginning immediately or at a future date.
FINRA adds that some contracts are a way to save for retirement, others turn existing savings into income, and some do both. This is why two clients can ask about “an annuity” and need very different products.
The contract has two phases:
- Accumulation phase. The buyer funds the contract. Under a deferred annuity, the money grows tax-deferred during this period, according to Investor.gov.
- Payout phase. Income payments begin.
The buyer may instead withdraw the contract value as a lump sum. Investor.gov notes this can bring surrender charges, taxes and tax penalties.
Payout options
The payout choice shapes the income. The Washington State Office of the Insurance Commissioner names “lifetime income with 10 years certain” as a popular option. It pays monthly for the owner’s life or for 10 years, whichever is longer. Triple-I describes fixed period annuities, which pay for a set time, such as ten years, regardless of the buyer’s age or continued life.
Types of annuities
The NAIC sorts annuities in two ways. By timing, they are immediate or deferred. By how the money is credited, they are fixed, variable or indexed.
Immediate and deferred
An immediate annuity is bought with a one-time payment and pays income within one year. The North Carolina Department of Insurance says these suit people who retire and want to convert savings into a guaranteed income stream. A deferred annuity has an accumulation period before payouts begin.
Fixed, indexed, RILA and variable
Investor.gov lists the four main deferred types in order of increasing risk:
| Type | How it credits growth | Downside |
|---|---|---|
| Fixed | Guarantees at least a minimum interest rate during accumulation | Lowest risk of the four |
| Fixed indexed | Interest is based in part on a benchmark such as the S&P 500, never less than zero | Credited interest depends on the index |
| Registered index-linked (RILA) | Value rises or falls in part with a benchmark | Contract owner can lose money |
| Variable | Contributions go to a menu of mutual funds | No limit on losses or gains |
Triple-I explains that in a fixed annuity the insurer guarantees the principal and a minimum rate of interest. It also notes that fixed annuities are regulated by state insurance departments.
What annuities cost
Costs are the first thing many prospects ask about. Agents who can state them plainly build trust.
Surrender charges. The NAIC Buyer’s Guide explains that a surrender charge applies when money comes out during a set period. It is a percentage of the amount withdrawn and usually falls each year until the period ends. The guide suggests looking for waivers for events such as a death, and for the right to take out a small amount, usually up to 10%, each year without a charge. The Washington commissioner puts the charge usually at 5% to 10% and says insurers can, on average, apply it within seven years of opening the contract. The Florida Department of Financial Services notes that most contracts allow a withdrawal of 10% per year without the surrender fee.
Other charges. The Washington commissioner lists mortality costs, administrative costs, an investment-cost ratio and the added cost of riders. The NAIC guide adds contract fees, premium tax, transaction fees, and, on variable annuities, mortality and expense risk charges and underlying fund charges.
Rider charges. A rider adds a benefit for an extra fee. The most common is the guaranteed lifetime withdrawal benefit (GLWB). The IRI 2025 Retirement Saving and Income Handbook says it provides income through regular lifetime withdrawals, even if the annuity value falls to zero. It is optional, for an additional fee, on many variable and fixed indexed annuities, and on some RILAs and fixed annuities.
For safe use of a GLWB, the handbook states that excess withdrawals reduce the guaranteed amount, usually pro rata, and in some cases the benefit is no longer payable for life. It also notes that payments cease at the death of the owner or owners, and that there may be a limited menu of investment options when the rider is elected.

How annuities are taxed
Tax treatment is a common question, and it depends on how the annuity was funded. The California Department of Insurance guide (updated July 2025) gives the basics:
- Deferred annuities delay taxes until the owner receives income.
- Money taken out before age 59½ brings a tax penalty, unless the owner becomes disabled or moves the money to another annuity.
- Income payments are taxed as regular income, not capital gains.
- If the annuity was bought with pre-tax dollars, the whole payment is taxed. If it was bought with after-tax dollars, only the interest portion is taxed.
The details differ between qualified and non-qualified contracts, and between withdrawals and annuitized payments. Clients with specific tax questions should speak with a tax professional.
Benefits and tradeoffs for retirement income
The U.S. Government Accountability Office reviewed annuities with guaranteed lifetime withdrawals. It found they can help older Americans avoid outliving their assets. Consumers may get steady income regardless of investment performance or how long they live, while keeping access to assets for other expenses. The same report notes the products are complex and require important decisions, and that several insurers and regulators advised getting professional financial advice before buying.
Timing matters. The GAO report states that the age at which lifetime withdrawals begin can affect the value of other benefits and guarantees. Its example is a buyer who purchases at 60 and waits until 85 to start withdrawals. That is a useful point to walk through with clients who ask when to turn income on.
The California guide also advises care with replacing an existing annuity, since new fees and penalties can apply. A clear side-by-side comparison of the old and new contract protects the client.

Explaining annuities to prospects
Most annuity prospects are comparing options, often over several conversations. They respond to short, accurate explanations of the points above: the phase the contract is in, what the guarantee covers, when the surrender period ends, and what each rider costs.
Agents who publish educational pages or emails should keep claims sourced and plain. Resources on compliant finance content can help agencies plan how to communicate annuity features, risks and terms responsibly.
Following up with annuity prospects
An annuity sale rarely closes in one call. The prospect asks for a quote, thinks about it, talks to a spouse, and asks again. Leads cool when follow-up is slow or inconsistent.
A workable routine has five steps:
- Capture the lead with its source. Note whether it came from a funnel, a webinar, a referral or an ad.
- Reply the same day. A short text or email that confirms the request and offers a time to talk.
- Send the explanation the prospect asked for. For example, the difference between fixed and indexed contracts, or how surrender charges decline.
- Follow up on a schedule. Text, email and voicemail over several days, stopping when the prospect replies.
- Move the deal through a pipeline. Quote sent, application started, signed, delivered.
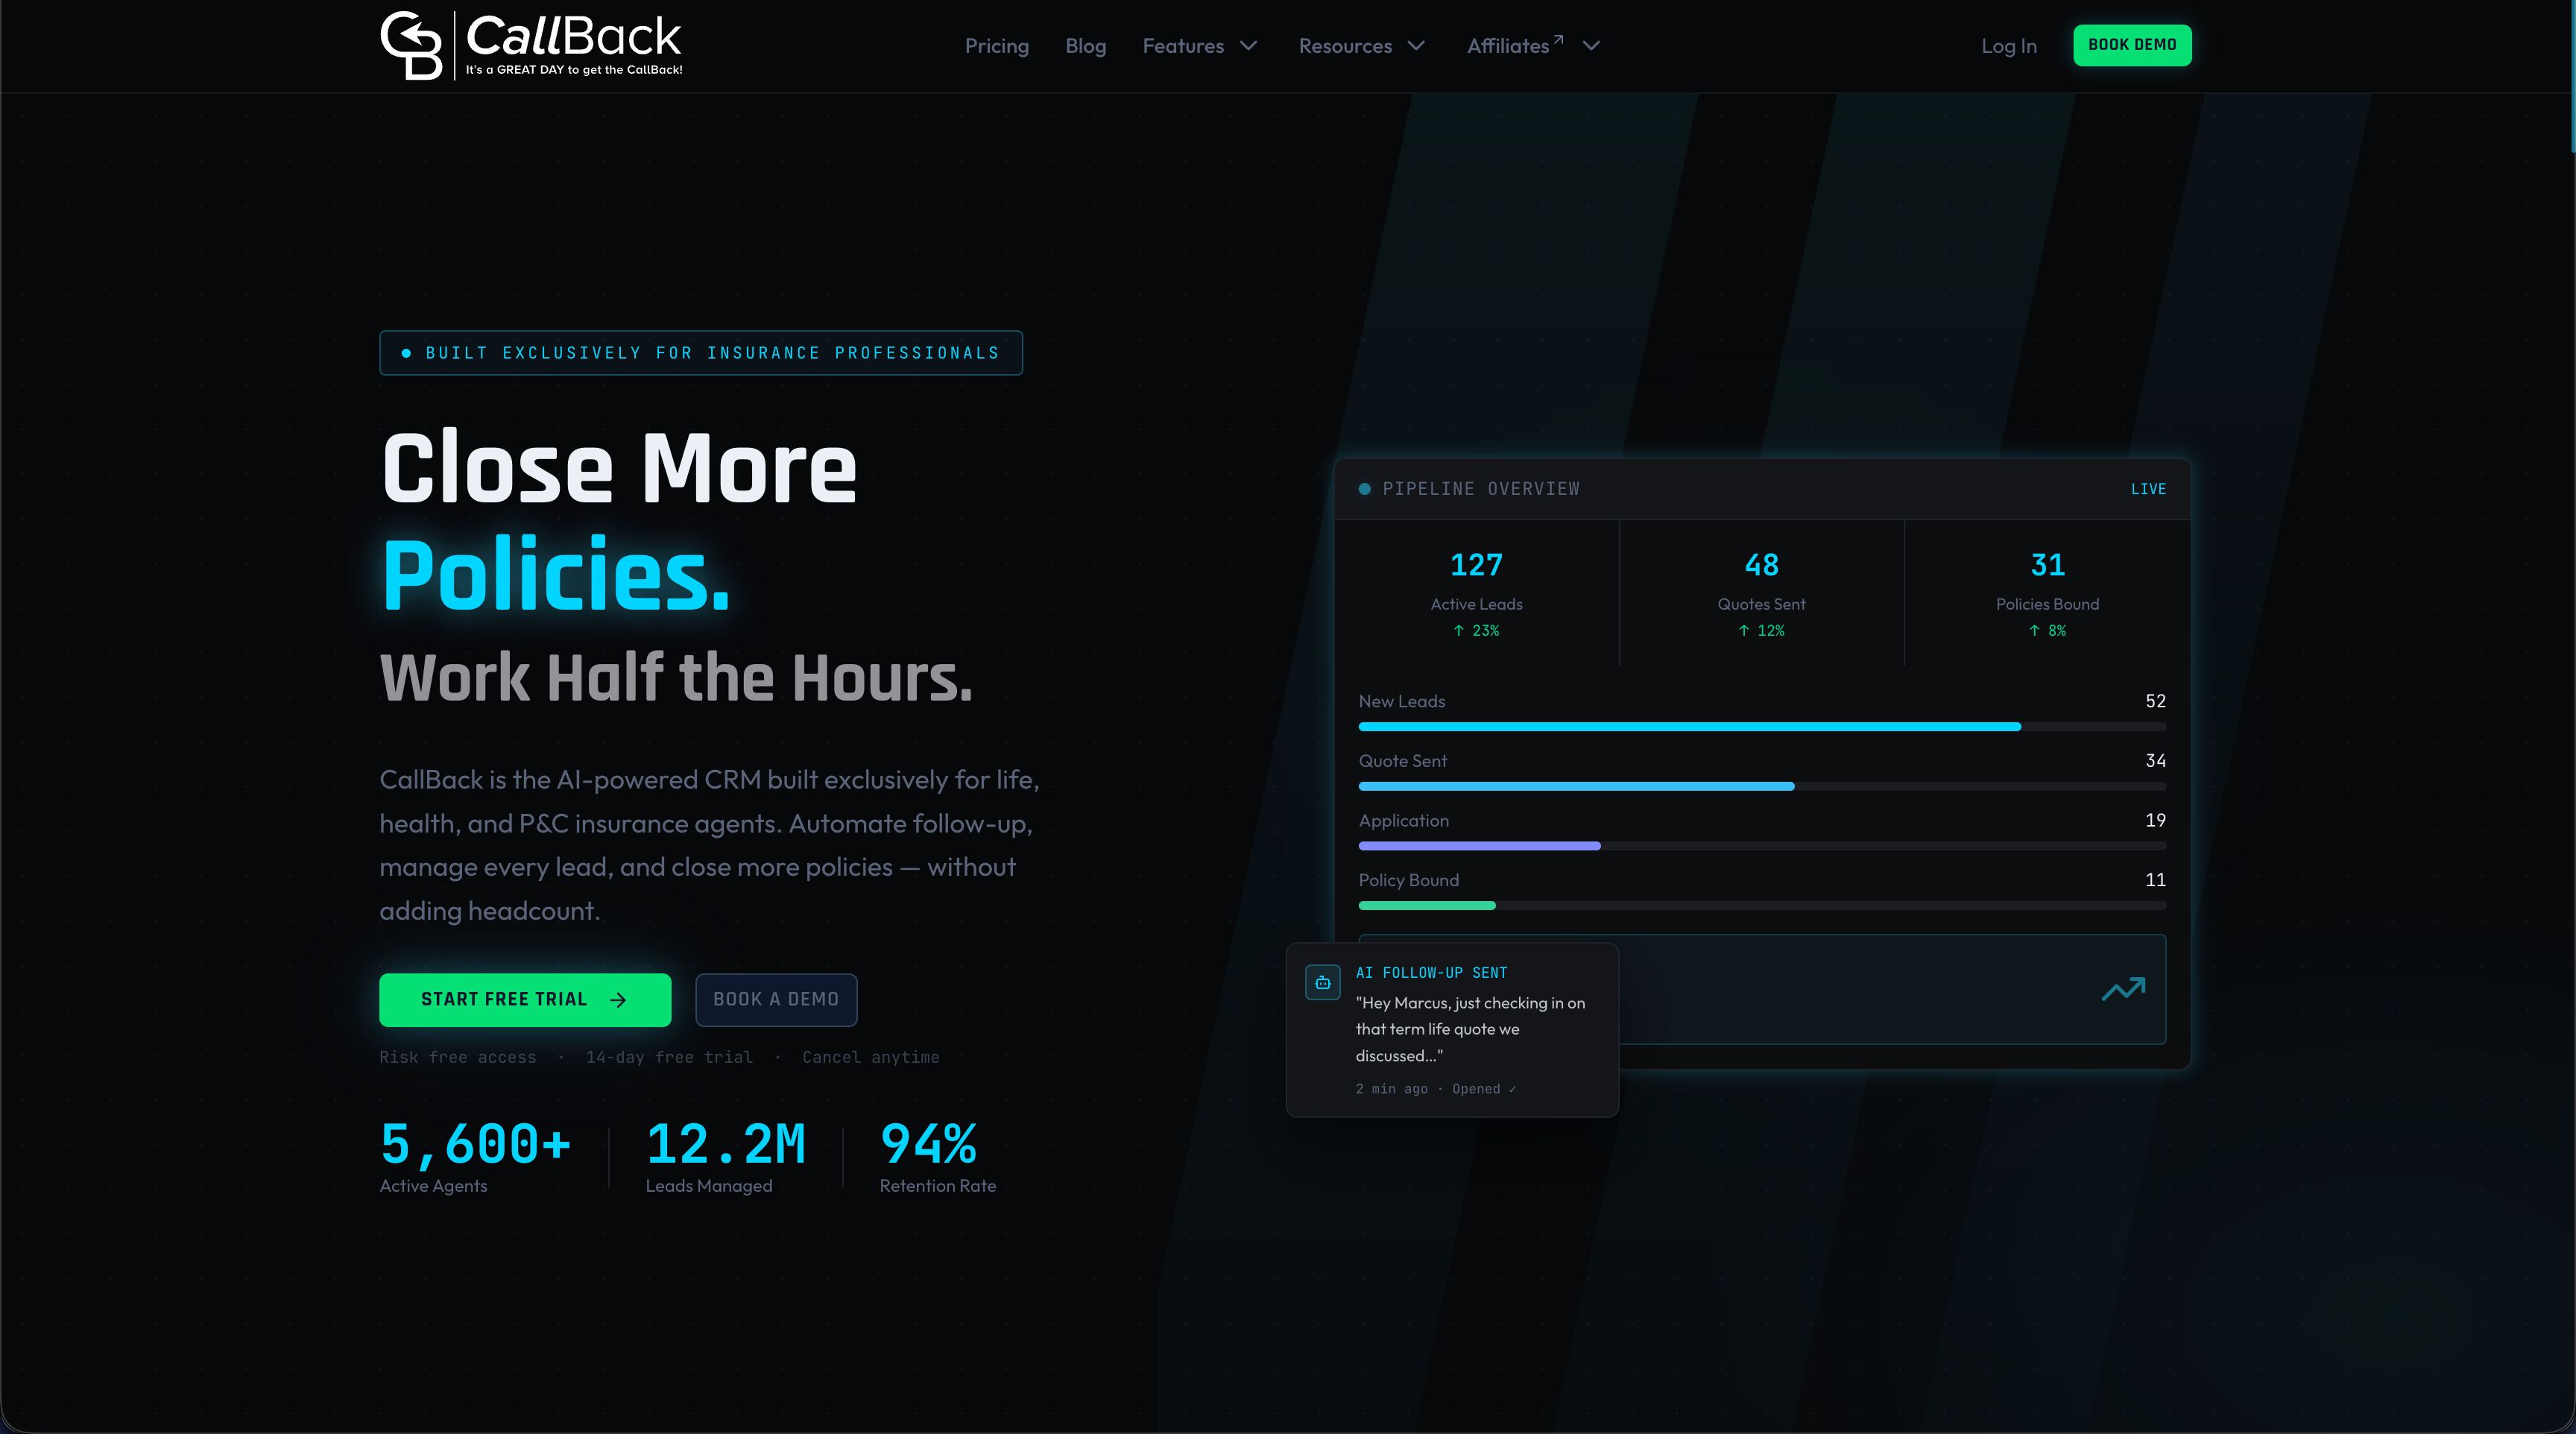
CallBack automates follow-up by SMS, email and voicemail, and its pipelines are built for insurance sales workflows. It also includes funnel and website builders, webinars, proposal and contract tools, and reputation management. For deliverability, CallBack uses unique message hashing, iMessage deliverability and phone-carrier-approved verbiage. For more on setting up the lead side, see the guides on automating lead generation and building a sales automation workflow.
CallBack for annuity agents
CallBack is an AI-powered CRM and sales automation platform for insurance agents, agencies and IMOs. Annuities are among its listed specialties, alongside final expense, mortgage protection, indexed universal life and Medicare.
The Professional plan costs $97 per month. Enterprise plans cost $297 per month for 10 full CRM accounts, $397 per month for 25 and $497 per month for 60. An Unlimited AI Employee Bundle is $127 per month. Phone numbers are $2.30 per month per number, and SMS, email and AI usage are billed as listed on the fees page. Plans start from a free trial. Agents can compare the options on the Professional plan page, or see all CallBack features.
Agencies with several producers can start with the Enterprise plans.
Our view
Annuity buyers make a large, long-term decision. They ask good questions, and they expect answers that match what the contract says. The agent who explains surrender periods, riders and taxes plainly is the one who gets the second call.
Most lost annuity deals are lost in the gap after the first conversation. The quote goes out, and nothing happens for a week. We built CallBack for insurance sales so that gap is covered by follow-up that runs on its own: text, email and voicemail, tied to pipelines for the products agents sell.
Automation does not replace the agent’s explanation of the product. It gives the agent time to give that explanation to more people, and keeps every prospect moving.
Kyle
FAQ
What are rider charges on an annuity?
A rider is an addition to the contract that provides extra benefits for an additional cost, according to the Washington State Office of the Insurance Commissioner. A common one is the guaranteed lifetime withdrawal benefit. The rider fee is separate from other contract charges, so the contract documents should list it.
What is a fixed term annuity?
A fixed period annuity pays income for a specified time, such as ten years, according to Triple-I. The payment does not depend on the age or continued life of the buyer. It differs from a lifetime payout, which continues for as long as the owner lives.
What fees are associated with annuities?
Fees can include surrender charges, contract fees, premium tax, transaction fees, rider costs and, on variable annuities, mortality and expense risk charges and fund charges. The NAIC Buyer’s Guide lists these. Surrender charges usually decline each year until the surrender period ends.
Are income annuities a good idea?
They can fit clients who want steady income they cannot outlive. The GAO found guaranteed lifetime income can help older Americans avoid outliving their assets, and advised professional financial advice before buying. The right product depends on the client’s income needs, other assets and timing.
Sources
- Annuities | Investor.gov
- Annuities | FINRA
- Learn how annuities work | Washington State Office of the Insurance Commissioner
- Annuities | NAIC
- Types of Annuities | North Carolina Department of Insurance
- Annuities basics | Triple-I
- Buyer’s Guide to Fixed Deferred Annuities | NAIC
- Annuity Overview | Florida Department of Financial Services
- The Retirement Saving and Income Handbook | IRI
- What Seniors Need to Know about Annuities | California Department of Insurance
- Retirement Security: Annuities with Guaranteed Lifetime Withdrawals | GAO
- GAO-13-75 full report